What is the market overview, definition, scope, and industry significance of Missile Warning Satellite Market?
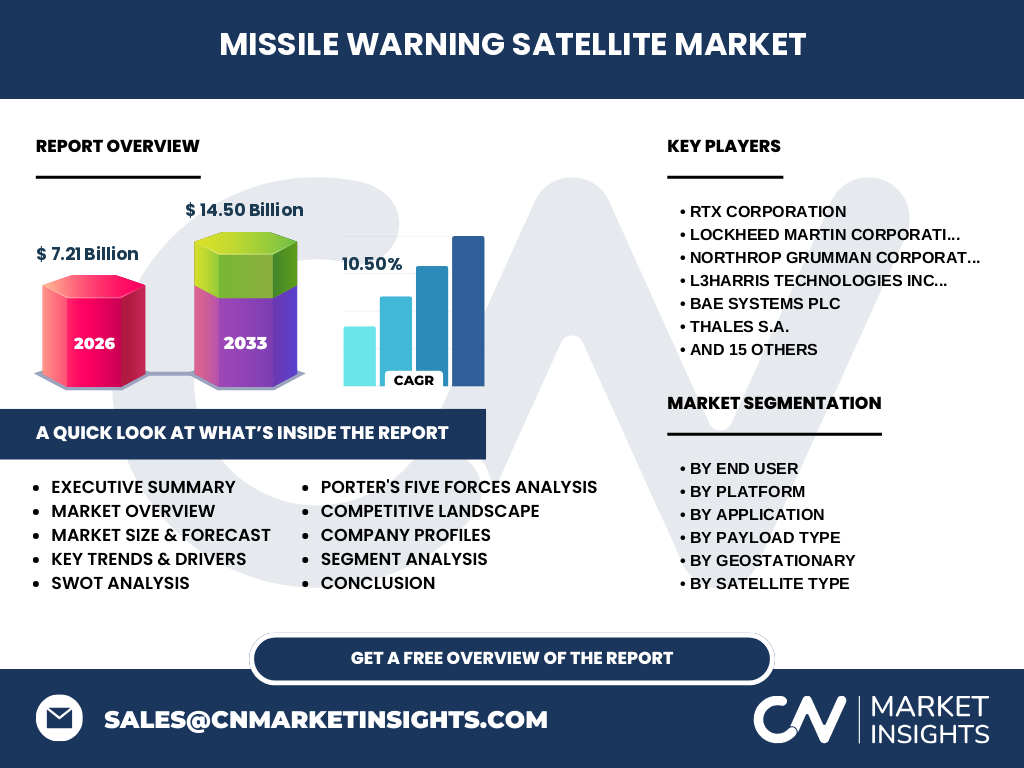
Our analysis indicates that the Missile Warning Satellite Market reached a valuation of 7.21 Billion in 2026. This sector encompasses critical space-based assets utilized for strategic defense monitoring and ballistic missile detection. Its industry significance is paramount for national security, leveraging advanced infrared and radar sensors to provide early warning against hypersonic threats across geostationary, low earth, and medium earth orbits.
Key market drivers, restraints, challenges, and opportunities shaping Missile Warning Satellite Market
Based on our research, the market is primarily driven by escalating geopolitical tensions and the rapid proliferation of hypersonic glide vehicles. However, stringent export controls on critical raw materials like beryllium and gallium present notable supply chain restraints. Opportunities abound for agile commercial aerospace primes integrating resilient constellations, while the primary technical challenge remains mitigating radiation-induced degradation in deep-space environments.
Emerging trends and growth patterns in Missile Warning Satellite Market
The data suggests a decisive shift toward disaggregated, multi-orbit architectures replacing monolithic geostationary sentinels. Emerging trends highlight the adoption of optical inter-satellite links for real-time telemetry routing. This transition favors innovators deploying software-defined payloads capable of updating threat-tracking algorithms dynamically in orbit, directly boosting the resilience of early warning systems against sophisticated electronic warfare.
How did the COVID-19 pandemic affect Missile Warning Satellite Market and its recovery trajectory?
The pandemic severely disrupted global aerospace supply chains, delaying payload integrations and specialized component deliveries for tactical surveillance satellites. Despite these logistical bottlenecks, defense budgets remained largely insulated. Our findings show that recovery accelerated as governments prioritized resilient space architectures, fast-tracking funding for rapid response satellites and securing long-term defense agency contracts.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive landscape is moderately consolidated, dominated by defense prime contractors like RTX Corporation, Lockheed Martin Corporation, and Northrop Grumman Corporation. Strategic dynamics involve aggressive vertical integration and strategic acquisitions of specialized sensor startups. Major players leverage deep government relationships and robust manufacturing infrastructure to secure high-value payload integration contracts across space-based and ground-based segments.
Executive summary — high-level synthesis of key findings about Missile Warning Satellite Market
Our comprehensive Missile Warning Satellite Market analysis reveals a robust expansion trajectory, driven by modernization initiatives across global defense agencies. The market is projected to surge from 7.21 Billion in 2026 to 14.50 Billion by 2033, achieving a stellar CAGR of 10.50%. Growth is heavily concentrated in low earth orbit constellations and advanced infrared detection payloads.
What is the projected market forecast from 2027 to 2033 for the Missile Warning Satellite Market industry trends?
Our proprietary forecast indicates the Missile Warning Satellite Market market size will expand from 2027 through 2033 to reach 14.50 Billion by the end of the forecast period. Propelled by a strong 10.50% CAGR, growth will peak as next-generation hypersonic tracking constellations transition from prototype phases to full operational deployment across defense portfolios.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation is categorized by end user, platform, application, payload type, geostationary, satellite type, low earth orbit, and medium earth orbit. End users span government and defense agencies, while platforms cover airborne, ground-based, naval, and space-based assets. Payloads include infrared, radar, and optical sensors, fulfilling critical roles in ballistic missile detection and threat intelligence.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily weighted toward North America, driven by massive defense outlays from the U.S. Space Force and Missile Defense Agency. The Asia-Pacific region represents the fastest-growing market, fueled by regional security dynamics and rising domestic procurement. Europe maintains a steady trajectory, emphasizing sovereign multi-mission satellites and collaborative regional defense frameworks governed by the European Defence Agency.
In-depth regional review — detailed examination of key regional markets
North America dominates due to established primes like L3Harris Technologies Inc. and Space Exploration Technologies Corp. driving rapid constellation deployments. In contrast, the Asia-Pacific market exhibits accelerated adoption of medium earth orbit secure communication satellites. Meanwhile, European investments focus on optical sensors and earth observation payloads to ensure strategic autonomy in early warning capabilities.
Company profiles — strategic positioning of leading companies in Missile Warning Satellite Market
Industry leaders occupy distinct strategic niches. Lockheed Martin Corporation and Northrop Grumman Corporation anchor large-scale geostationary architectures. Meanwhile, disruptors like Anduril Industries Inc. and Rocket Lab USA Inc. pioneer agile, low-cost tactical surveillance satellites. Thales S.A. and Leonardo S.p.A. focus on advanced European payload integration, whereas Mitsubishi Electric Corporation spearheads precision radar development in the Asia-Pacific theater.
Porter's Five Forces analysis of the competitive environment
The threat of new entrants is moderate, constrained by high capital expenditure requirements and stringent security clearances mandated by defense agencies. Bargaining power of suppliers is high for specialized radiation-hardened microelectronics and raw optical glass. Rivalry among existing competitors is intense, characterized by aggressive bidding on multi-billion-dollar early warning modernization contracts.
SWOT analysis highlighting internal and external strategic factors
Strengths include robust technological innovation and entrenched government partnerships. Weaknesses involve lengthy procurement cycles and high program development costs. Opportunities lie in commercializing dual-use space situational awareness technologies. Threats encompass escalating orbital debris hazards and sophisticated cyberattacks targeting satellite command and control networks.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain begins with raw material extraction—such as rare earths and aerospace-grade titanium—flowing into component fabrication of radiation-hardened processors and infrared focal plane arrays. Primes then integrate these payloads into satellite buses. Final distribution flows through ground station telemetry networks to ultimate end-users within defense agencies and strategic command centers.
Investment insights — strategic recommendations and high-potential areas
Investors should focus on firms developing low earth orbit missile tracking satellites and advanced optical sensor payloads. Our analysis indicates that companies leveraging commercial-off-the-shelf components for rapid-response architectures will capture disproportionate market share, offering superior risk-adjusted returns amidst escalating global defense modernization budgets.
Conclusion and key takeaways
The Missile Warning Satellite Market represents a critical, high-growth sector within defense aerospace, set to expand to 14.50 Billion by 2033 at a 10.50% CAGR. Technological shifts toward multi-orbit resilience and hypersonic tracking present lucrative avenues for forward-thinking primes and agile innovators alike.
Research methodology detailing data triangulation and validation protocols
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with aerospace chief technology officers, and secondary macroeconomic indicators. We cross-reference defense budget allocations from agencies like the Pentagon with corporate earnings disclosures to ensure absolute analytical precision.
Scope of the report — coverage parameters and limitations
This report covers the global Missile Warning Satellite Market industry trends across all major satellite types, payloads, applications, and geographic regions from 2026 to 2033. Limitations include restricted visibility into classified black-budget military space programs and proprietary payload specifications withheld due to strict national security regulations.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent milestones include major contract awards to companies like Ball Aerospace and Sierra Nevada Corporation for resilient missile-tracking sensor payloads. Additionally, strategic partnerships between traditional defense primes and commercial launch providers have accelerated the cadence of rapid-response satellite deployments into low earth orbit.